- explain why businesses need finance (start-up capital, expansion, working capital, cash-flow problems)
- distinguish short-term and long-term finance and internal and external sources of finance
- describe sources of finance (retained profit, sale of assets, owners' savings, bank loan/overdraft, share issue, debentures, leasing, hire purchase, trade credit, microfinance, crowdfunding, government grants)
- explain the factors that influence the choice of source of finance
Financial information and decisions
IGCSE Business Studies · Topic 5
 12:52
Financial information and decisions
This business was doing well. Every month it made a profit — the products sold, the customers were happy. But watch the money in the bank. Suppliers wanted…
English narration · English + 中文 subtitles burned in
5.1
Why businesses need finance

Syllabus
Source: Cambridge International syllabus
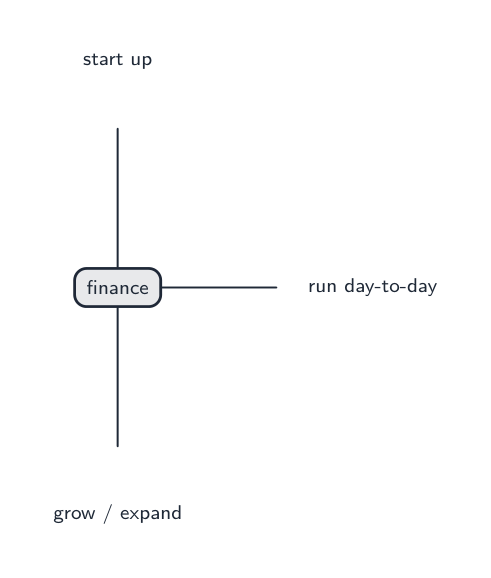
Finance 资金 means the money a business needs. A business needs finance to:
- start up — start-up capital 启动资金 to buy equipment and stock before it earns anything,
- grow — money for expansion 扩张, such as new shops or machines,
- run day to day — working capital 营运资金 to pay wages and suppliers while waiting for customers to pay,
- survive a cash-flow 现金流 problem, when more money is going out than is coming in.
Sources of finance
Finance can be short-term 短期 (paid back within a year) or long-term 长期 (over several years). It can come from inside the business (internal) or from outside (external).
| Source | Internal / external | Notes |
|---|---|---|
| retained profit 留存利润 | internal | profit kept in the business, not paid out |
| sale of assets 资产 | internal | selling things the business no longer needs |
| owners' savings | internal | the owners' own money |
| bank loan 贷款 | external | borrowed money, repaid with interest 利息 over time |
| bank overdraft 透支 | external | the bank lets the account go below zero, for short-term needs |
| issuing new shares 股份 | external | only for limited companies; raises money but shares out control |
| debentures 债券 | external | long-term loans to a company that pay interest |
| leasing 租赁 | external | renting equipment instead of buying it |
| hire purchase 分期付款 | external | buy now and pay in monthly parts |
| trade credit 贸易信贷 | external | pay suppliers later, for example after 30 days |
| microfinance 小额信贷 | external | small loans for tiny businesses in poorer areas |
| crowdfunding 众筹 | external | many people each give a small amount, often online |
| government grants 补助金 | external | money from the government that need not be repaid |

Choosing a source
The best source depends on how much money is needed and for how long, the cost (interest and fees), the size and legal type of the business (only companies can sell shares), and how much risk and control the owners will accept.
Explore
Sources of finance lab
Choose the best type of finance by time, risk and ownership.
Vocabulary
Train
| English |
|---|
| finance/ˈfaɪnæns/ |
| start-up capital/stɑːt ʌp ˈkæpɪtl/ |
| expansion/ekˈspænʃn/ |
| working capital/ˈwɜːkɪŋ ˈkæpɪtl/ |
| cash-flow/kæʃ fləʊ/ |
| short-term/ʃɔːt tɜːm/ |
| long-term/lɒŋ tɜːm/ |
| retained profit/rɪˈteɪnd ˈprɒfɪt/ |
| assets/ˈæsets/ |
| loan/ləʊn/ |
| interest/ˈɪntrest/ |
| overdraft/ˈəʊvədræft/ |
| shares/ʃeəz/ |
| debentures/deˈbentʃəz/ |
| leasing/ˈliːsɪŋ/ |
| hire purchase/ˈhaɪə ˈpɜːtʃɪs/ |
| trade credit/treɪd ˈkredɪt/ |
| microfinance/ˌmaɪkrəʊfaɪˈnæns/ |
| crowdfunding/ˈkraʊdfʌndɪŋ/ |
| grants/ɡrænts/ |
5.2
Cash flow and working capital

Syllabus
- explain the importance of cash and the difference between cash and profit
- construct, complete and interpret a cash-flow forecast (inflows, outflows, net cash flow, opening/closing balance)
- explain working capital and how a business can overcome cash-flow problems
Source: Cambridge International syllabus
Cash is not the same as profit
Cash 现金 is the money a business can use right now. Profit 利润 is revenue 收入 minus costs over a period. A business can be making a profit yet still run out of cash — for example, if customers have not paid yet. Running out of cash can force even a profitable business to close.
The cash-flow forecast
A cash-flow forecast 现金流预测 predicts the money coming in and going out each month. It uses:
- inflows 流入 — money coming in (sales, loans),
- outflows 流出 — money going out (wages, rent, materials),
- net cash flow 净现金流 — inflows minus outflows,
- opening balance 期初余额 — the cash held at the start of the month,
- closing balance 期末余额 — the cash held at the end of the month.
$$\text{net cash flow} = \text{inflows} - \text{outflows}$$
$$\text{closing balance} = \text{opening balance} + \text{net cash flow}$$
Worked example. A shop expects inflows of £12,000 and outflows of £9,000 next month, and starts the month with £2,000 in the bank. Find the net cash flow and the closing balance.
$$\text{net cash flow} = \text{\pounds} 12\,000 - \text{\pounds} 9\,000 = \text{\pounds} 3\,000$$
$$\text{closing balance} = \text{\pounds} 2\,000 + \text{\pounds} 3\,000 = \text{\pounds} 5\,000$$

Working capital
Working capital is the value of current assets 流动资产 minus current liabilities 流动负债. It supports day-to-day operations. Current assets include cash, stock and money owed by customers. Current liabilities include short-term debts, such as amounts due to suppliers. It is not the cash balance: stock must be sold and customers must pay before those assets become cash. A business with positive working capital can still struggle to pay a bill due today.
$$\text{working capital} = \text{current assets} - \text{current liabilities}$$
To overcome cash-flow problems, a business can arrange an approved overdraft, negotiate later supplier payments, ask customers to pay sooner, sell spare assets, or cut non-essential spending. Consider the amount and timing of the gap, interest or discounts, supplier agreement and the effect on future sales or production. A forecast is an estimate and should be updated when actual receipts or payments differ.

Explore
Cash-flow forecasting
A forecast of cash in and out each month warns a business of a cash shortage before it strikes.
Explore
Cash-flow forecast lab
Drag the monthly cash in, cash out and the one-off oven purchase — does the bakery stay out of the red all six months?
Vocabulary
Train
| English |
|---|
| cash/kæʃ/ |
| profit/ˈprɒfɪt/ |
| revenue/ˈrevənjuː/ |
| cash-flow forecast/kæʃ fləʊ ˈfɔːkæst/ |
| inflows/ˈɪnfləʊz/ |
| outflows/aʊtˈfləʊz/ |
| net cash flow/net kæʃ fləʊ/ |
| opening balance/ˈəʊpənɪŋ ˈbæləns/ |
| closing balance/ˈkləʊzɪŋ ˈbæləns/ |
| current assets/ˈkʌrənt ˈæsets/ |
| current liabilities/ˈkʌrənt ˌlaɪəˈbɪlɪtiz/ |
5.3
Income statement
Syllabus
- identify the main features of an income statement: revenue, cost of sales, gross profit, expenses and profit for the year
- explain how income statements are used by stakeholders
Source: Cambridge International syllabus
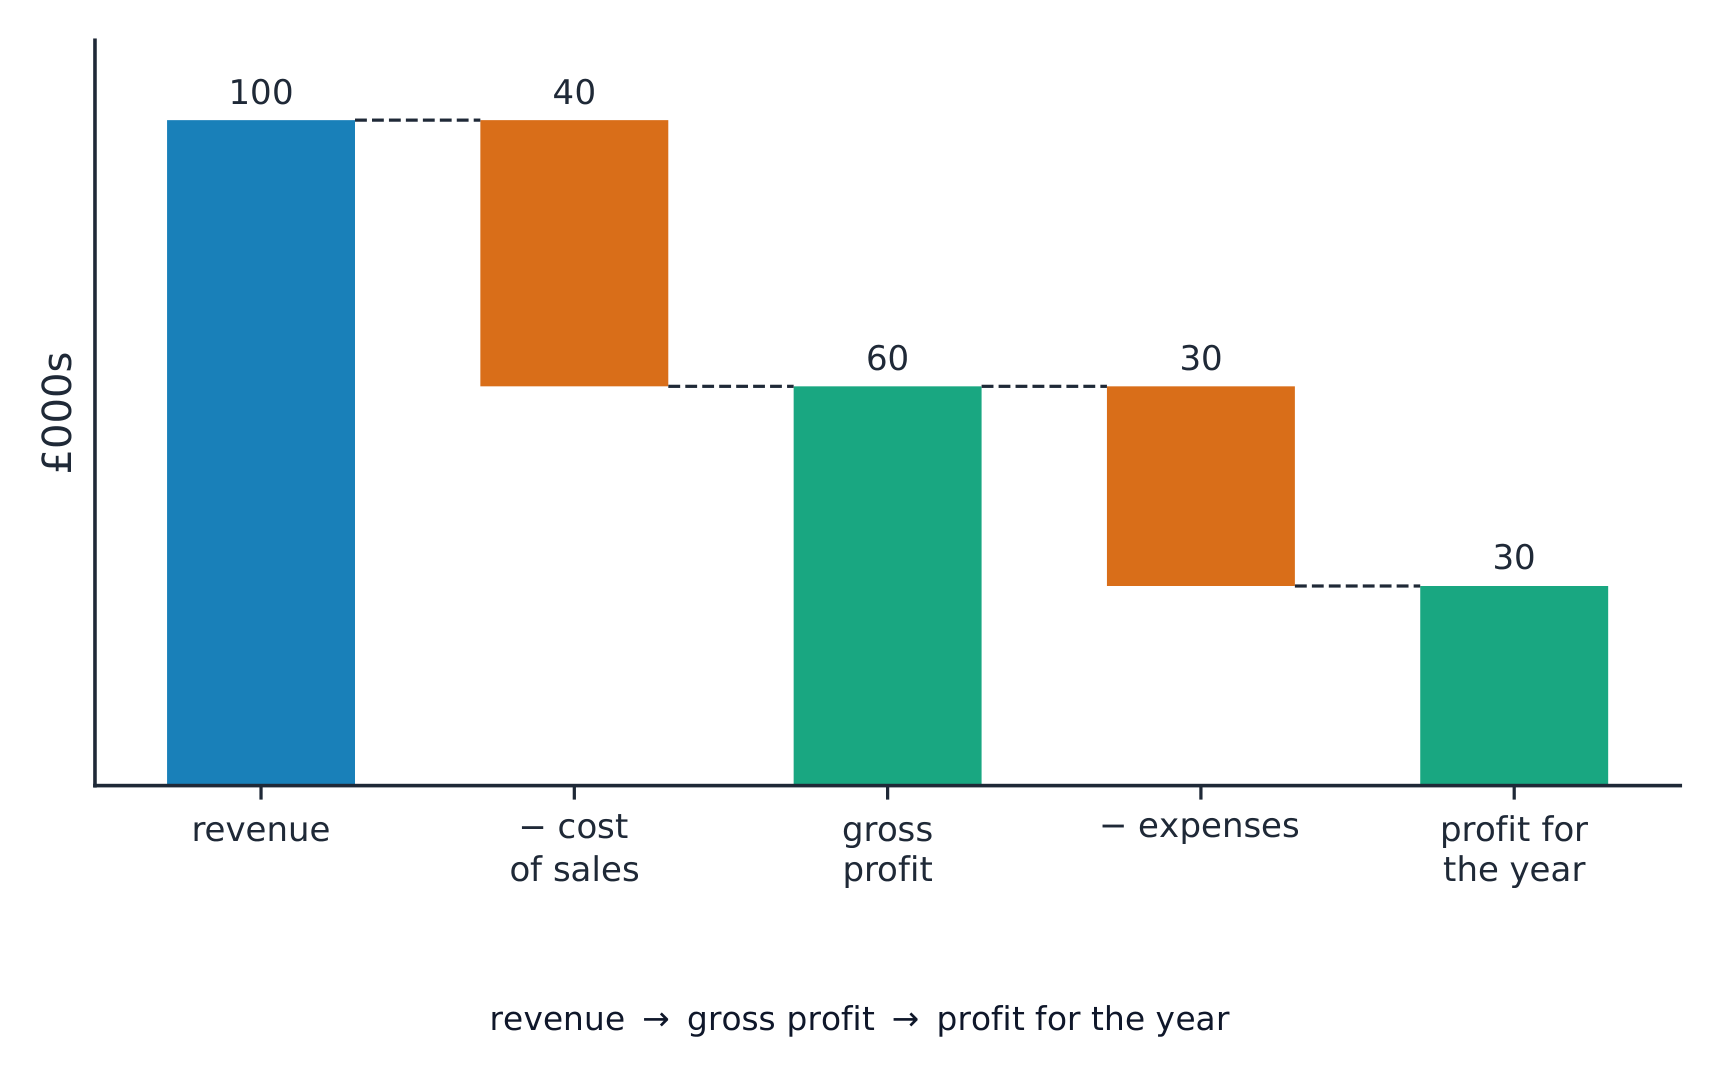
An income statement 损益表 shows how much profit a business made over a period, usually a year.
| Line | Meaning |
|---|---|
| revenue | value of sales in the period, including credit sales not yet paid for |
| cost of sales 销售成本 | the cost of making or buying the goods that were sold |
| gross profit 毛利润 | revenue minus cost of sales |
| expenses 费用 | other running costs: shop rent, office salaries, advertising |
| profit for the year 年度利润 | gross profit minus expenses |
$$\text{gross profit} = \text{revenue} - \text{cost of sales}$$
$$\text{profit for the year} = \text{gross profit} - \text{expenses}$$
Worked example. A business has revenue of £200,000, cost of sales of £120,000 and expenses of £50,000. Find its gross profit and its profit for the year.
$$\text{gross profit} = \text{\pounds} 200\,000 - \text{\pounds} 120\,000 = \text{\pounds} 80\,000$$
$$\text{profit for the year} = \text{\pounds} 80\,000 - \text{\pounds} 50\,000 = \text{\pounds} 30\,000$$
Profit rewards owners for taking business risks. Retained profit is profit kept after distributions to owners, such as dividends 股息. It provides internal finance for equipment or expansion. A company with £30,000 profit that pays £12,000 in dividends retains £18,000. This does not prove £18,000 is spare cash: funds may be tied up in stock, customer debts or equipment.
Higher revenue does not guarantee higher profit. Compare equal periods: if revenue rises by £20,000 but cost of sales and expenses together rise by £24,000, profit falls by £4,000. Investigate the reasons before cutting spending that may support future sales. Unsold stock is not all charged as cost of sales; do not deduct a production cost again as another expense.
Income statements are used by stakeholders 利益相关者: owners compare rewards and reinvestment, managers investigate changing costs, and lenders judge whether earnings may support repayments. Lenders also need cash-flow and existing-debt information; past profit cannot guarantee future repayments.
Explore
Financial statements flow
See how business events become the statements users read.
Vocabulary
Train
| English |
|---|
| income statement/ˈɪŋkʌm ˈsteɪtmənt/ |
| cost of sales/kɒst ɒv seɪlz/ |
| gross profit/ɡrəʊs ˈprɒfɪt/ |
| expenses/ekˈspensɪz/ |
| profit for the year/ˈprɒfɪt fəðə jɪə/ |
| stakeholders/ˈsteɪkhəʊldəz/ |
| dividend/ˈdɪvɪdend/ |
5.4
Statement of financial position

Syllabus
- identify the main classifications in a statement of financial position: non-current and current assets, current and non-current liabilities, and owners' equity/capital
- explain how the statement of financial position is used
Source: Cambridge International syllabus
A statement of financial position 财务状况表 (also called a balance sheet) shows what a business owns and what it owes (its liabilities 负债) on one day.
- non-current assets 非流动资产 — things kept for the long term: buildings, machines.
- current assets — short-term items: inventory 库存, money owed by customers, and cash.
- current liabilities — debts due within a year: an overdraft, money owed to suppliers.
- non-current liabilities 非流动负债 — debts due after more than a year: a long-term loan.
- owners' equity 所有者权益 — the owners' recorded stake: assets minus liabilities. It includes owners' investment and profit kept in the business.
The statement helps users see which assets the business has and how they are financed. Recorded equity is not a guaranteed selling price for the business. A lender examines existing borrowing; a supplier checks current debts and resources before offering credit. Both need due dates and a cash-flow forecast to judge payment ability.
Interpretation example. A shop has £84,000 of non-current assets, £18,000 stock, £12,000 owed by customers and £6,000 cash: total assets £120,000. Supplier debts £24,000 plus a long-term loan £46,000 make liabilities £70,000, leaving equity £50,000. Only £6,000 is cash now. Stock may sell slowly and customers may pay late, so the asset total does not prove the shop can pay £24,000 today.
A new £10,000 cash loan increases assets and liabilities by £10,000 each; equity is unchanged. Selling surplus stock at its recorded cost converts stock into cash without increasing total assets or profit. Selling needed stock or essential machinery may harm future trading. A loan with instalments due within a year and later has both current and non-current parts.

Explore
Financial statements flow
See how business events become the statements users read.
Vocabulary
Train
| English |
|---|
| statement of financial position/ˈsteɪtmənt ɒv faɪˈnænʃl pəˈzɪʃn/ |
| liabilities/ˌlaɪəˈbɪlɪtiz/ |
| non-current assets/nɒn ˈkʌrənt ˈæsets/ |
| inventory/ˈɪnvəntri/ |
| non-current liabilities/nɒn ˈkʌrənt ˌlaɪəˈbɪlɪtiz/ |
| owners' equity/ˈəʊnəz ˈekwɪti/ |
5.5
Analysis of accounts

Syllabus
- calculate and interpret profitability ratios: gross profit margin, profit margin and return on capital employed (ROCE)
- calculate and interpret liquidity ratios: current ratio and acid test (quick) ratio
- explain how internal and external users use account analysis to make decisions
Source: Cambridge International syllabus
You can judge a business by working out ratios 比率 from its accounts. A ratio compares two figures.
Profitability ratios
Profitability 盈利能力 ratios show how good a business is at making profit.
$$\text{gross profit margin} = \frac{\text{gross profit}}{\text{revenue}} \times 100\%$$
$$\text{profit margin} = \frac{\text{profit for the year}}{\text{revenue}} \times 100\%$$
$$\text{ROCE} = \frac{\text{profit}}{\text{capital employed}} \times 100\%$$
- gross profit margin 毛利率 — gross profit as a percentage of revenue.
- profit margin 利润率 — profit for the year as a percentage of revenue.
- return on capital employed 资本回报率 (ROCE) — profit as a percentage of the capital employed 所用资本 (money invested). It shows how well the investment is used.
A higher percentage means more profit for each pound of sales or capital, using comparable figures. It does not guarantee a better future result: cutting quality or essential maintenance may raise profit now but harm future trading. Compare similar businesses and equal periods, and investigate the causes of changes.
Worked example. The same business (revenue £200,000, gross profit £80,000, profit for the year £30,000) has capital employed of £150,000. Find its three profitability ratios.
$$\text{gross profit margin} = \frac{80\,000}{200\,000} \times 100\% = 40\%$$
$$\text{profit margin} = \frac{30\,000}{200\,000} \times 100\% = 15\%$$
$$\text{ROCE} = \frac{30\,000}{150\,000} \times 100\% = 20\%$$
Liquidity ratios
Liquidity 流动性 ratios help judge a business’s ability to pay its short-term debts.
$$\text{current ratio} = \frac{\text{current assets}}{\text{current liabilities}}$$
$$\text{acid test ratio} = \frac{\text{current assets} - \text{inventory}}{\text{current liabilities}}$$
- the current ratio 流动比率 compares current assets with current liabilities. A ratio of 1.5:1 means £1.50 of current assets per £1 of current liabilities. A value around 1.5–2 is a common guide, not proof that every business can pay bills on time.
- the acid test ratio 速动比率 is stricter: it leaves out inventory, because inventory is not yet sold and may be slow to turn into cash. The remaining assets can still include unpaid customer debts.
Worked example. A business has current assets of £40,000 (including £10,000 of inventory) and current liabilities of £20,000. Find its current ratio and acid test ratio.
$$\text{current ratio} = \frac{40\,000}{20\,000} = 2.0$$
$$\text{acid test ratio} = \frac{40\,000 - 10\,000}{20\,000} = 1.5$$
A ratio has a meaning even without a comparison; a judgement needs context. Suppose current assets are £36,000, stock £18,000 and current liabilities £24,000. Current ratio is 1.5:1 and acid test 0.75:1. If later current assets are £48,000, including stock £36,000, customer debts £6,000 and cash £6,000, with liabilities unchanged, the ratios become 2:1 and 0.5:1. The higher current ratio hides weaker cover without selling stock.
Check the quality and saleability of stock, customer payment dates and bill due dates. A very high current ratio may suggest excess stock or idle cash. A business with fast cash sales can operate differently from one with slow-selling stock. Neither ratio is a guarantee about payment timing.
Who uses account analysis
- internal users (owners and managers) compare margins and ROCE over time, investigate costs, and assess prices or investment. Falling gross margin can reflect buying costs, selling prices or product mix; it does not identify one cause on its own.
- external users such as banks, suppliers and investors use the accounts to decide whether to lend, offer credit or invest. They also need forecasts, existing debts and repayment dates. Ratios use past or dated data and leave out factors such as service quality and customer loyalty.
Explore
Accounts ratio diagnosis
Classify ratios by the question they answer about a business.
Vocabulary
Train
| English |
|---|
| ratios/ˈreɪʃɪəʊz/ |
| profitability/ˌprɒfɪtəˈbɪlɪti/ |
| gross profit margin/ɡrəʊs ˈprɒfɪt ˈmɑːdʒɪn/ |
| profit margin/ˈprɒfɪt ˈmɑːdʒɪn/ |
| return on capital employed/rɪˈtɜːn ɒn ˈkæpɪtl emˈplɔɪd/ |
| capital employed/ˈkæpɪtl emˈplɔɪd/ |
| liquidity/lɪˈkwɪdɪti/ |
| current ratio/ˈkʌrənt ˈreɪʃɪəʊ/ |
| acid test ratio/ˈæsɪd test ˈreɪʃɪəʊ/ |
5.5
Exam tips
- Cash is not profit: a profitable business can still run out of cash if customers pay late. Watch the closing balance on a cash-flow forecast.
- Separate internal sources (retained profit, sale of assets, owners' savings) from external ones (bank loan, overdraft, shares, leasing, trade credit).
- Key formulas: net cash flow = inflows − outflows; closing balance = opening balance + net cash flow; working capital = current assets − current liabilities.
- Profitability ratios (gross margin, profit margin, ROCE) are percentages; current and acid-test ratios are numbers or ratios to 1. Compare like periods and businesses. A higher current ratio can hide growing unsold stock; check the acid test and cash timing.
- Only limited companies can raise money by issuing shares; a sole trader or partnership cannot.
Vocabulary card meanings
cash-flow: Money moving into and out of a firm over time. short-term: Covering a brief period, such as weeks or months. long-term: Covering years rather than weeks. loan: A sum borrowed now and repaid later, usually with interest. debentures: Long-term loans to a company, often secured on its assets. leasing: Paying to use an asset without owning it. hire purchase: Paying for an asset in instalments and owning it at the end. crowdfunding: Raising money from a large number of small contributors. return on capital employed: Profit compared with the long-term capital used in the business. acid test ratio: A check of whether short-term assets, excluding stock, cover short-term debts.
Interactive lessons on this topic
Work through it step by step, with instant-check exercises.