Cash flows: the list is the craft
Introduced| English | Meaning |
|---|---|
| incremental cash flow | the cash that changes because of the project - because-of, after tax, in cash |
| depreciation tax shield | The tax saved because depreciation is deducted from taxable profit: the tax rate times the depreciation. |
| opportunity cost/ɒpəˈtjuːnɪti kɒst/ | The value of the best alternative forgone when a choice is made. |
NPV is arithmetic on a list — the craft is the list
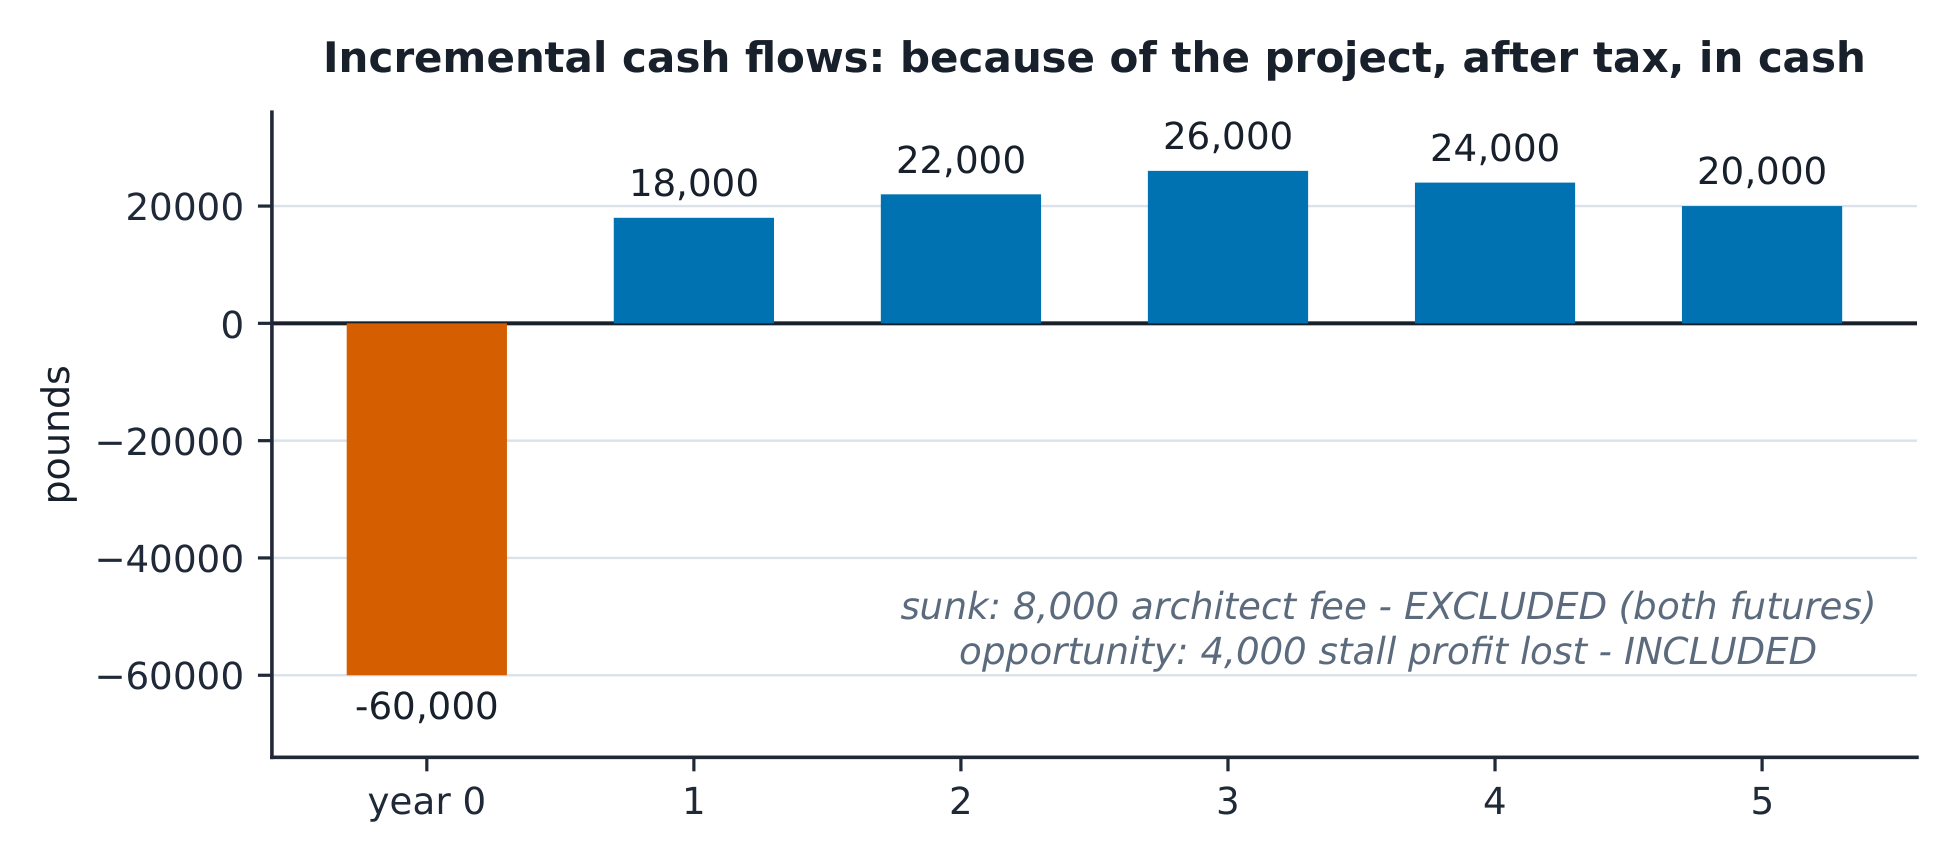
- Most valuation errors are cash-flow errors: the 8,000 architect fee included (sunk), the 4,000 stall profit missed (opportunity), festival capacity double-counted.
- The incremental cash flow 增量现金流 means: because of the project, after tax, in cash.
The three tests for every line
- Sunk: in both futures → never enters. Opportunity: the alternative forgone → always enters. Financing: in the DISCOUNT rate, not the flows.
- Depreciation is not cash — its only entry is the tax shield it creates.
In the list or out?
Route each item by the three tests - incremental, sunk, financing - and catch the tax and working-capital subtleties.
The founder says the 8,000 architect fee must push the NPV down. The correct reply?
Difficulty 1/5 · 100 coins + a small bonus on first completion today
Sunk means gone at the decision moment. The rule is bookkeeping, not heartlessness.
The site kills 4,000 a year of stall profit for 5 years. At 8%, its present-value cost, to the nearest pound?
Difficulty 2/5 · 140 coins + a small bonus on first completion today
A 4,000 five-year annuity discounted at 8% = 15,971 - the opportunity cost enters the NPV as a real deduction.
Loan interest belongs in the project cash flows.
Difficulty 1/5 · 100 coins + a small bonus on first completion today
Financing costs live in the discount rate (the WACC of unit 5). Putting them in the flows double-counts them.
Match each item to its treatment.
Difficulty 2/5 · 140 coins + a small bonus on first completion today
Three tests and one subtlety - the whole unit on four lines.
Cannibalisation and diverted capacity
- The Saturday crew earns 3,000 that would exist anyway → not incremental. The 1,200 of festival orders genuinely lost → in, negative.
- The net entry is −1,200: the test is always "does the cash change BECAUSE of the project?"
The Saturday crew would earn 3,000 anyway; 1,200 of festival orders are genuinely lost. The net entry?
Difficulty 1/5 · 100 coins + a small bonus on first completion today
The 3,000 exists in both futures; the 1,200 changes because of the project. Because-of is the only test.
Depreciation 12,000 a year, tax 25%. The annual tax shield, in pounds?
Difficulty 2/5 · 140 coins + a small bonus on first completion today
The shield = depreciation x tax rate = 3,000 of tax saved a year - the ONLY cash entry depreciation ever gets.
Working capital: 4,000 injected at year 0. The correct treatment?
Difficulty 1/5 · 100 coins + a small bonus on first completion today
Cash moves when it moves: out at the build, back at the wind-down. Profit never sees it; the flow list must.
The single question that decides any borderline item is:
Difficulty 1/5 · 100 coins + a small bonus on first completion today
Because-of, after tax, in cash - the three words that build the list the NPV will judge.
Working capital moves too
- 4,000 injected at year 0 (inventory build) is an outflow; its recovery in year 5 is an inflow. Profit never sees the movement; cash does.
The depreciation tax shield, priced
- The 60,000 fit-out depreciated straight-line over five years is 12,000 a year. At 25% tax the depreciation tax shield 折旧税盾 is $0.25 \times 12{,}000 = 3{,}000$ of tax not paid each year.
- At 8% that stream is worth $3{,}000 \times 3.993 = \mathbf{11{,}978}$ today. Depreciation is not cash, but the tax it saves is.
3,000 a year of tax shield for 5 years at 8%: present value (nearest whole)?
Difficulty 2/5 · 140 coins + a small bonus on first completion today
$3{,}000 \times (1 - 1.08^{-5})/0.08 = 11{,}978$.
Worked example: one year's incremental cash flow
- Extra contribution 20,000, minus the stall's 4,000 opportunity cost and 1,200 of diverted festival orders: 14,800 before tax.
- Taxable profit is $14{,}800 - 12{,}000 = 2{,}800$, so tax is 700, and the cash flow is $14{,}800 - 700 = \mathbf{14{,}100}$. Depreciation is subtracted to find the tax, then never from the cash.
Pre-tax incremental cash 14,800, depreciation 12,000, tax 25%: after-tax cash flow?
Difficulty 2/5 · 140 coins + a small bonus on first completion today
Tax $= 0.25 \times 2{,}800 = 700$; $14{,}800 - 700 = 14{,}100$.
Depreciation is subtracted from the year's cash flow.
Difficulty 1/5 · 100 coins + a small bonus on first completion today
It is subtracted only to work out the tax; the cash flow is pre-tax cash minus the tax.
Three cash-flow slips
- Sunk or financing flows in the list. Both double count.
- Opportunity costs missed. The stall's 4,000 is a real cost.
- Accounting profit read as cash. Depreciation shelters tax, and that is all.
Recap
- Incremental = because-of, after-tax, in-cash.
- Sunk never, opportunity always, financing in the rate.
- Working capital enters when it moves, both ends.